

The RSD 6 Million and 8 Million Thresholds in Serbia: What Changes and Your Options
If you invoice as an entrepreneur in Serbia, two numbers quietly run your tax life: RSD 6 million and RSD 8 million. Cross the first and you lose the flat-tax (pausal) regime. Cross the second and you enter the VAT system. Neither is optional, neither waits for you to notice, and the cost of noticing late runs into thousands of euros.
This guide explains what each threshold triggers, what changes from 1 January 2027, and which structures are available on the other side.
Threshold one: RSD 6 million and the end of pausal
The pausal regime taxes you on an assumed income set by the Tax Administration, regardless of what you actually invoice. It is simple and, for many, cheap. It ends the moment your invoiced turnover in a calendar year exceeds RSD 6 million.
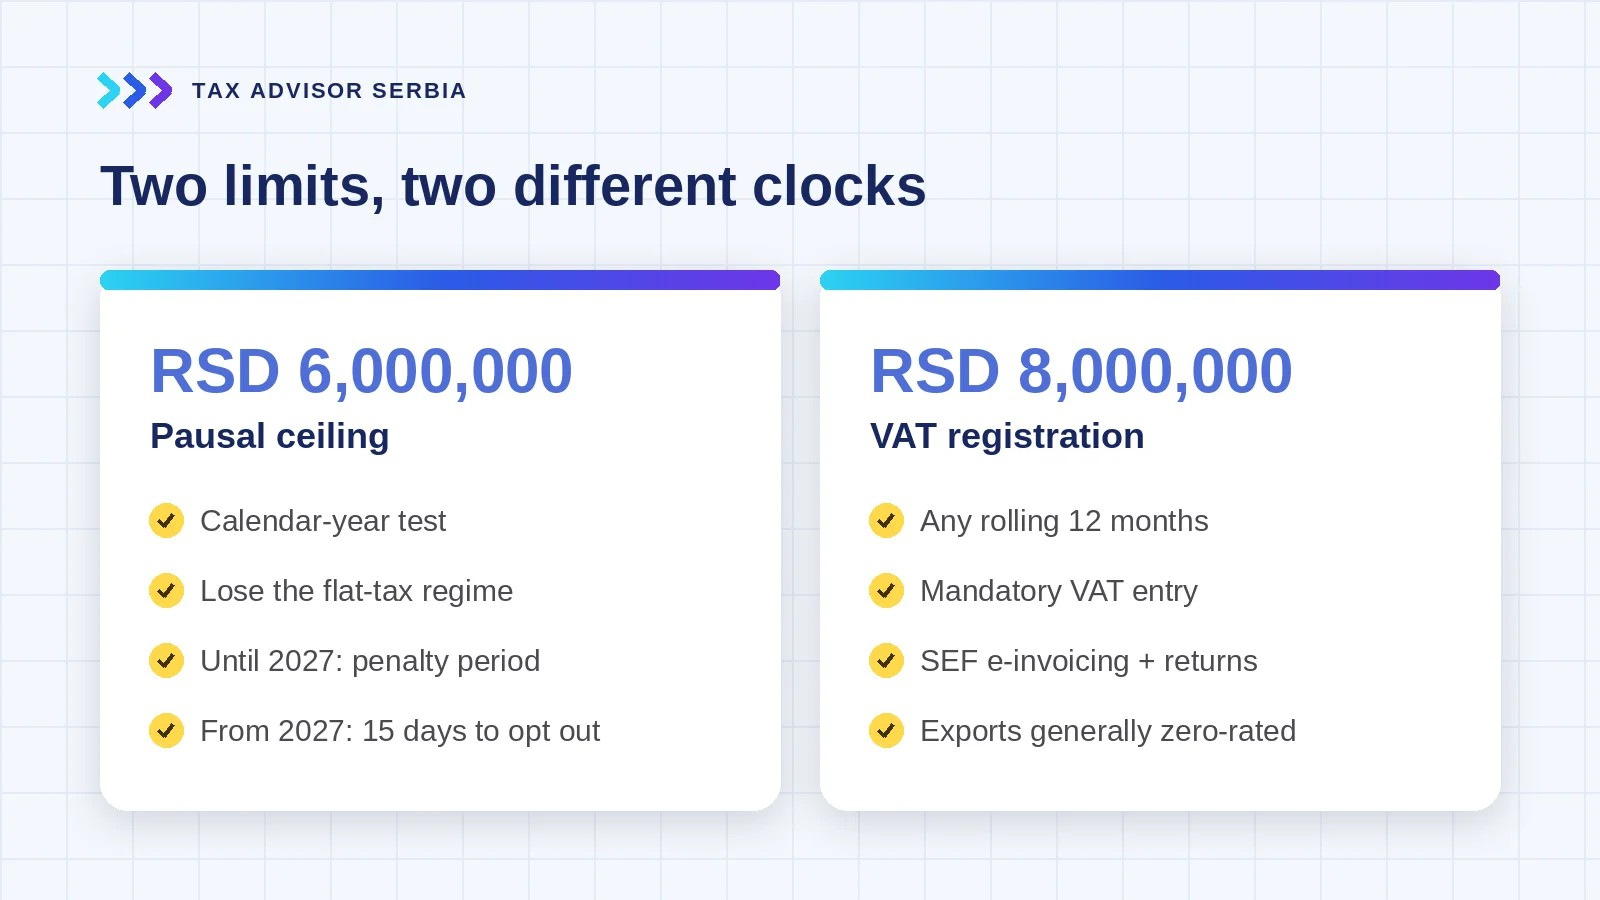
Crossing the limit today triggers what I call the penalty period: until the end of that year you pay tax and contributions on your entire profit, with no right to the personal salary arrangement that normally makes bookkeeping entrepreneurs efficient. A more favourable setup only opens on 1 January of the following year. One oversight in November can therefore cost you a configured setup for over a year.
From 1 January 2027 this changes. Under amendments adopted in 2026, an entrepreneur who loses pausal status gets 15 days to opt for personal salary for the period that follows, so the penalty year shrinks to a paperwork deadline. The deadline is short and missing it restores the old pain, but the trap is no longer structural.

Threshold two: RSD 8 million and VAT
The second threshold is separate and often crossed unnoticed: taxable turnover above RSD 8 million in any rolling 12-month period makes VAT registration mandatory. This is not a calendar-year test, so an entrepreneur who grew quickly can cross it mid-year while watching only the pausal limit.
VAT registration brings electronic invoicing through Serbia's SEF system, regular VAT returns, and input VAT recovery. For entrepreneurs invoicing foreign clients the practical burden is usually smaller than feared, because exported services are generally zero-rated, but registration, invoicing discipline and filings are not optional once you cross.
The third number nobody tells you about
If most of your income comes from one client, the independence test matters more than either threshold. An entrepreneur who fails it can see income reclassified as employment income, with the tax bill recalculated accordingly. Any structuring decision made at the 6M or 8M line should start with this test, not end with it.
Your options at the crossing
Three structures exist on the other side of pausal: bookkeeping entrepreneur with personal salary, bookkeeping entrepreneur without it, and a limited company (DOO). They produce materially different effective tax rates on the same income, and the right one depends on your margin, your client structure, your residency and what you do with the profit. The comparison for your numbers is exactly what I prepare as a fixed-fee written report.
What I can say generally: the default you fall into by doing nothing is rarely the one you would choose on purpose.
What to do before you cross
Three things are worth doing while both thresholds are still ahead of you. Track invoiced turnover monthly against both limits, because they run on different clocks. Run the independence test before committing to any entrepreneur structure. And decide your next structure before the threshold decides for you, because some choices, once the year turns or the contract is signed, cannot be repaired retroactively.
Frequently asked questions
What happens if I cross RSD 6 million as a pausal entrepreneur?
You lose the pausal regime. Until the end of 2026, that means paying tax and contributions on your full profit until year end, with no personal salary option. From 1 January 2027, you get 15 days from losing the status to opt for personal salary for the period that follows.
Is the RSD 8 million VAT threshold the same as the pausal limit?
No. The pausal limit is RSD 6 million per calendar year; the VAT threshold is RSD 8 million in any 12-month period. They are tested differently and trigger different obligations.
Can I stay pausal and just stop invoicing near the limit?
Deferring invoices shifts the problem, it does not solve it, and artificial deferral around year end attracts exactly the kind of attention you do not want. The sustainable answer is choosing the right structure.
I have one main client. Does that change anything?
Yes, more than the thresholds do. The independence test decides whether entrepreneur status is defensible at all, and it should be assessed before any transition.
Approaching either threshold? I prepare a fixed-fee written comparison of your options (bookkeeping entrepreneur, personal salary, DOO) with the numbers for your situation, and the independence test where one client dominates. Reply within 24 hours. Get in touch.